3 Overlooked Tax-Saving Tips from BNA’s Head of Tax
Technology
Tax


Tax planning doesn’t always have to involve complicated strategies. Sometimes, valuable opportunities are already available through accounts and benefits you have access to today.
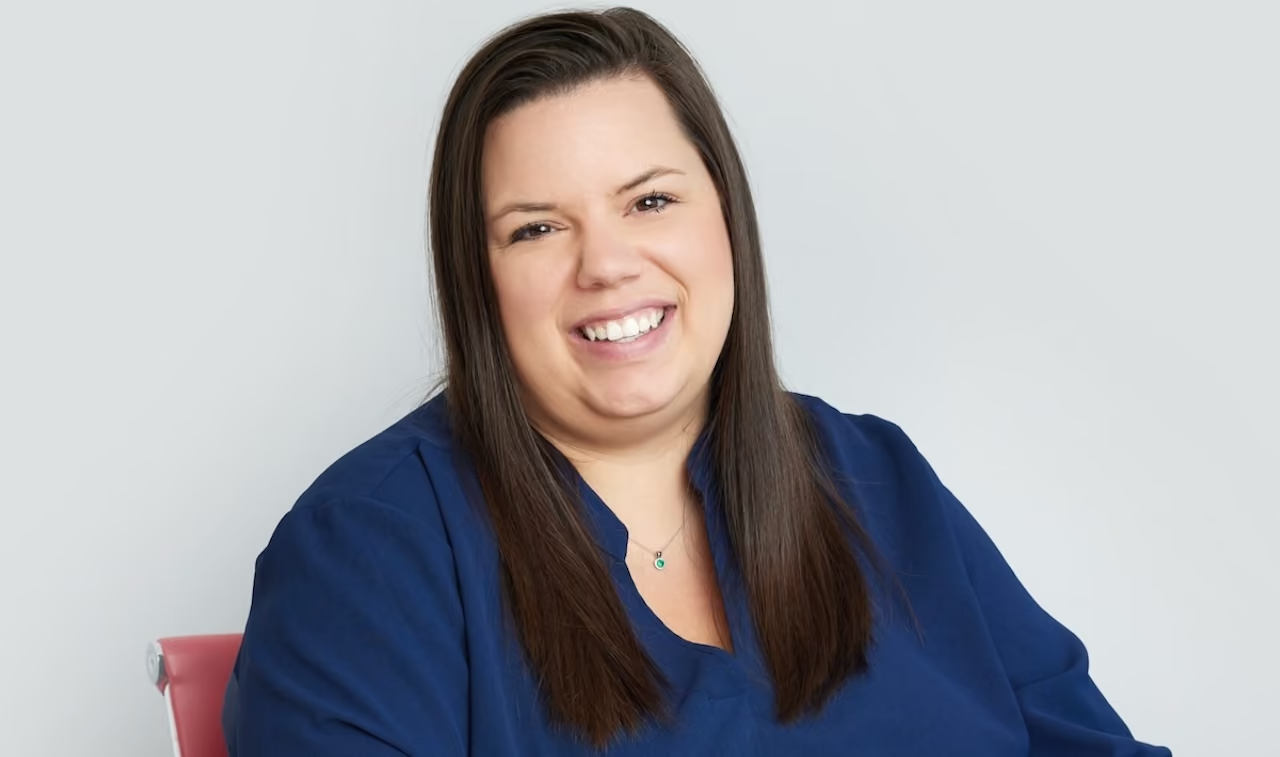
"I think people often overlook the tax-saving opportunities that are already available to them,” says Ashley Taylor, CPA, BNA’s Head of Tax.
“Things like maxing out an HSA, contributing to retirement accounts, or putting money into a 529 plan can add up over time. These are relatively simple planning opportunities, but they are often overlooked because people don’t know what is available to them or don’t think about them until it’s too late."
Here are three areas worth keeping on your radar.
If you’re eligible for a Health Savings Account (HSA), don’t overlook its tax advantages.
Contributions may provide a tax benefit, earnings can grow tax-deferred, and withdrawals for qualified medical expenses are generally tax-free. Plus, unused funds can typically roll over from year to year.
If you have an HSA but aren’t taking full advantage of it, it may be worth reviewing your contribution.
Retirement savings can support your long-term goals while also creating tax-planning opportunities.
Depending on the type of account, contributions may provide a current tax benefit or allow your savings to receive favorable tax treatment in the future.
A raise, bonus or change in household income can be a good reason to revisit how much you’re contributing. Business owners and self-employed individuals may have additional retirement-plan options worth exploring as well.
The goal isn’t simply to contribute as much as possible. It’s to understand what’s available and use those options intentionally.
Planning for future education expenses? A 529 plan can provide a tax-advantaged way to save.
While contributions generally aren’t deductible for federal income tax purposes, investments can grow tax-deferred and qualified withdrawals are generally federal income-tax-free. Depending on where you live, additional state tax benefits may also be available.
And 529 plans aren’t just for parents. Grandparents and other family members can contribute toward a child’s future education, too.
Small planning decisions can add up over time, especially when you know what options are available and consider them before tax season.
If you’re unsure which opportunities may apply to you, talk with your CPA about your options and what makes sense for your broader financial goals.
Discover how our team can support your financial goals with clarity and precision.