How to Open a Trump Account for Your Child
Education
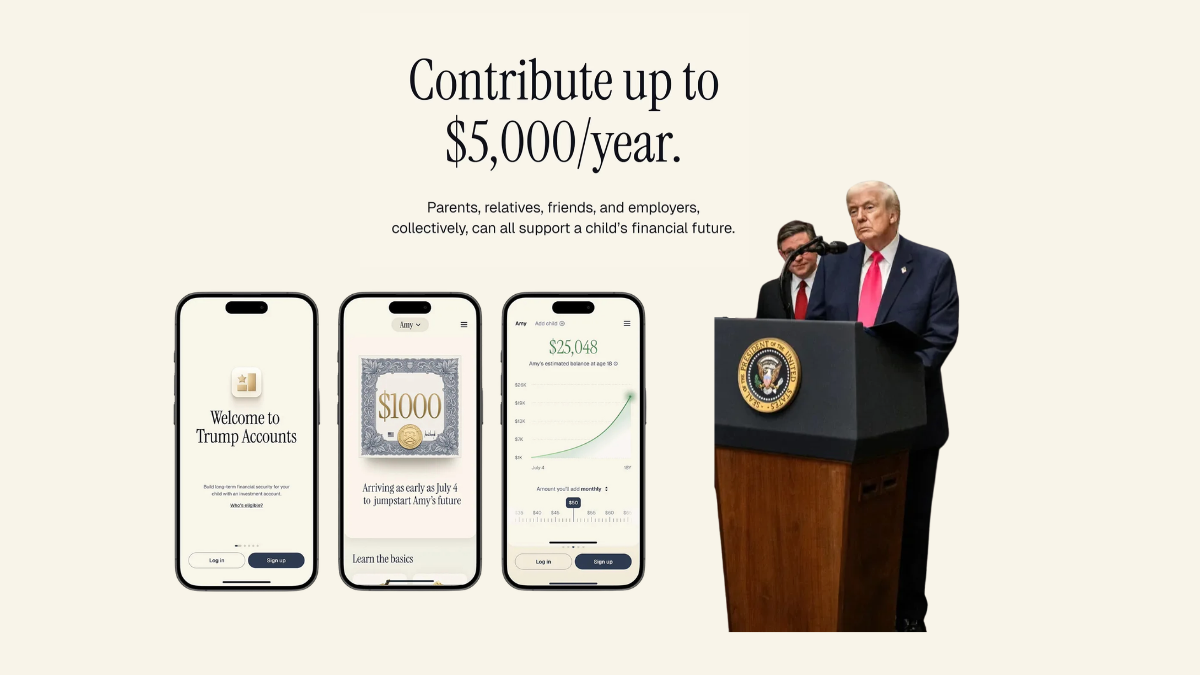


A Trump Account is a new type of tax-advantaged individual retirement account (IRA) that allows families to invest on behalf of children under age 18.
Eligible children born between January 1, 2025, and December 31, 2028, may also receive a one-time $1,000 contribution from the federal government.
A child is eligible for a Trump Account if they:
Children can qualify for an account even if they are not eligible for the $1,000 contribution.
Beginning October 1, 2026, the U.S. Treasury Department began automatically enrolling eligible children in Trump Accounts. An authorized individual must still claim and activate the account before managing it.
Parents, legal guardians, adult siblings, or grandparents may be authorized to complete the process.
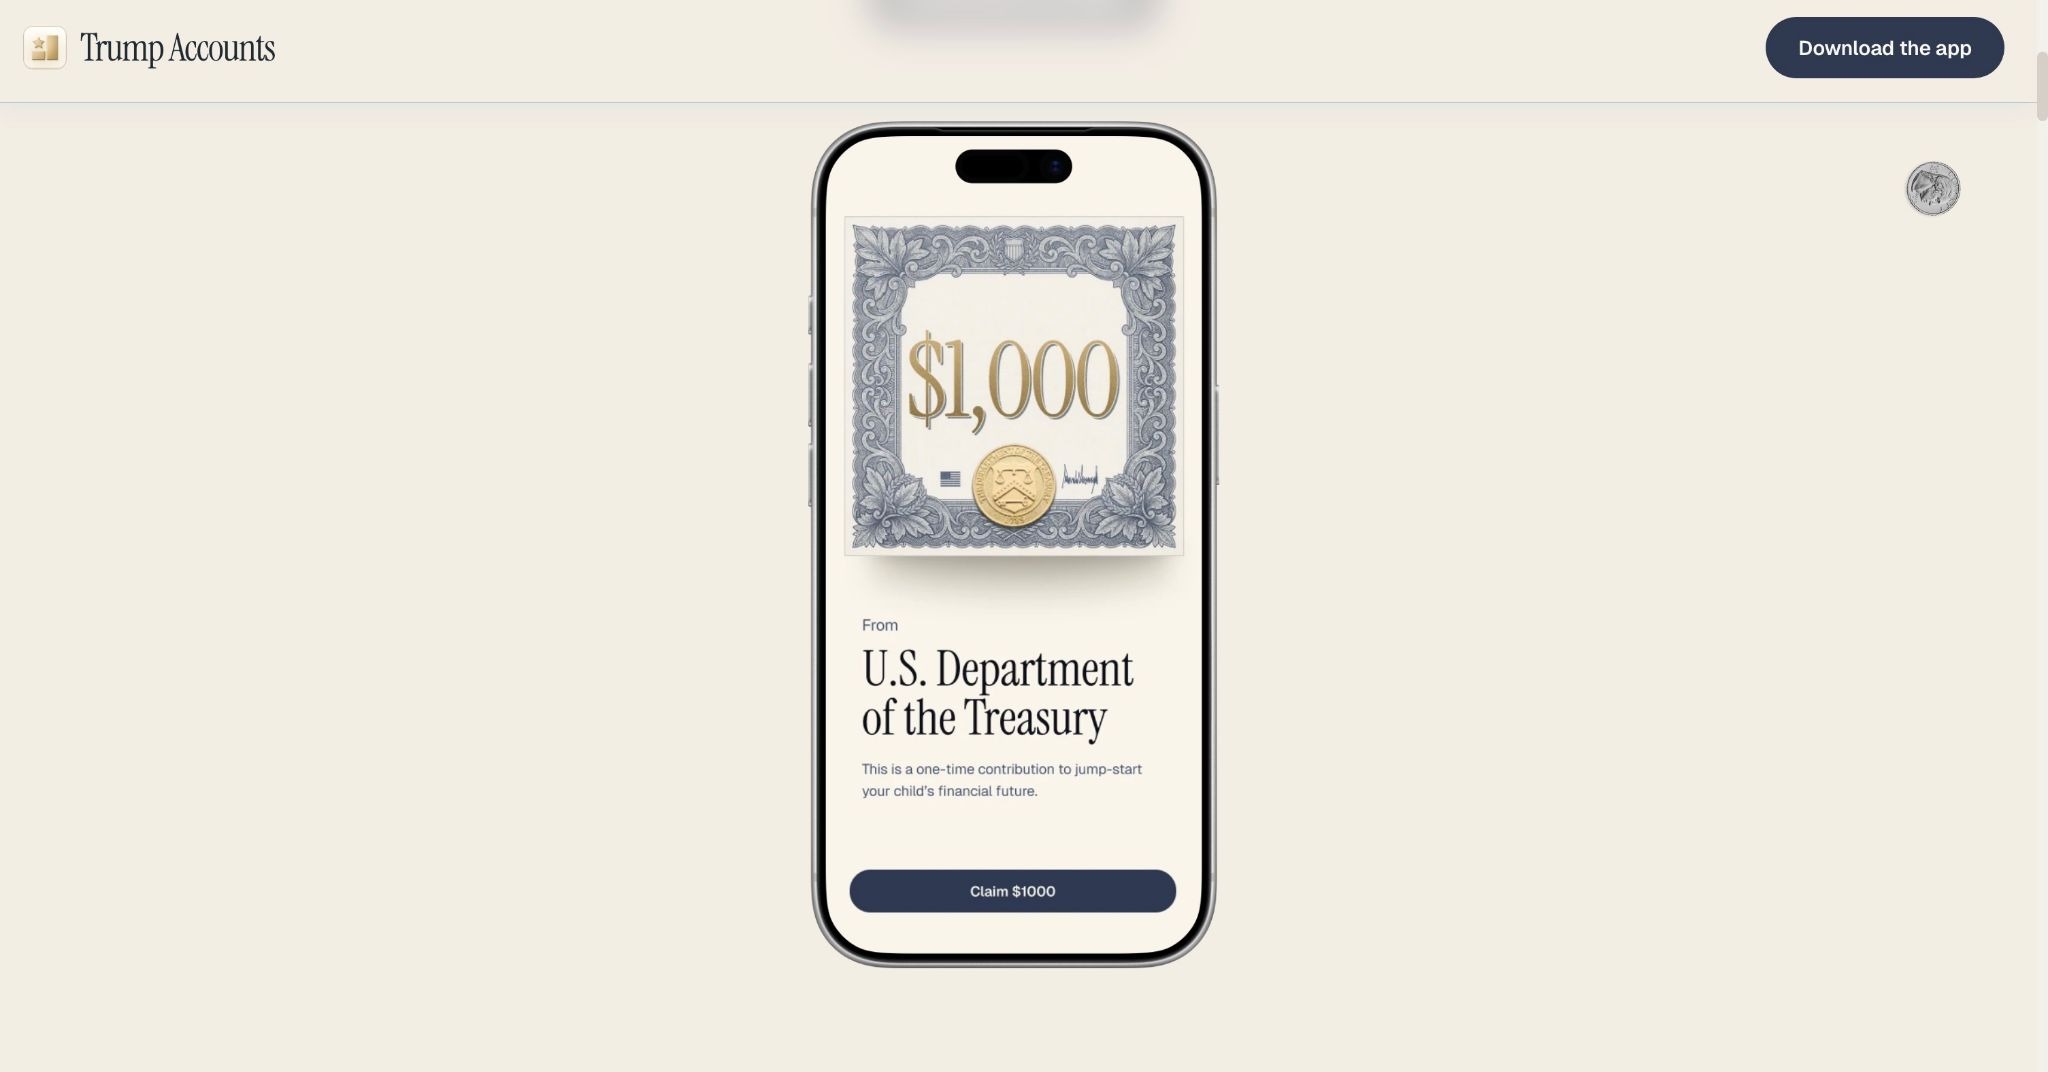
Children born between January 1, 2025, and December 31, 2028, may qualify for the one-time contribution if they are U.S. citizens with valid Social Security numbers.
The $1,000 contribution is not automatic. An authorized individual must elect to receive it using IRS Form 4547, even if an account was automatically opened. The government contribution does not count toward the annual contribution limit.
Families can contribute up to $5,000 per child annually in after-tax dollars, beginning July 4, 2026. Employers may contribute up to $2,500 annually toward an eligible dependent's account, which counts toward the $5,000 limit.
Children do not need earned income to receive contributions during the account's initial growth period.
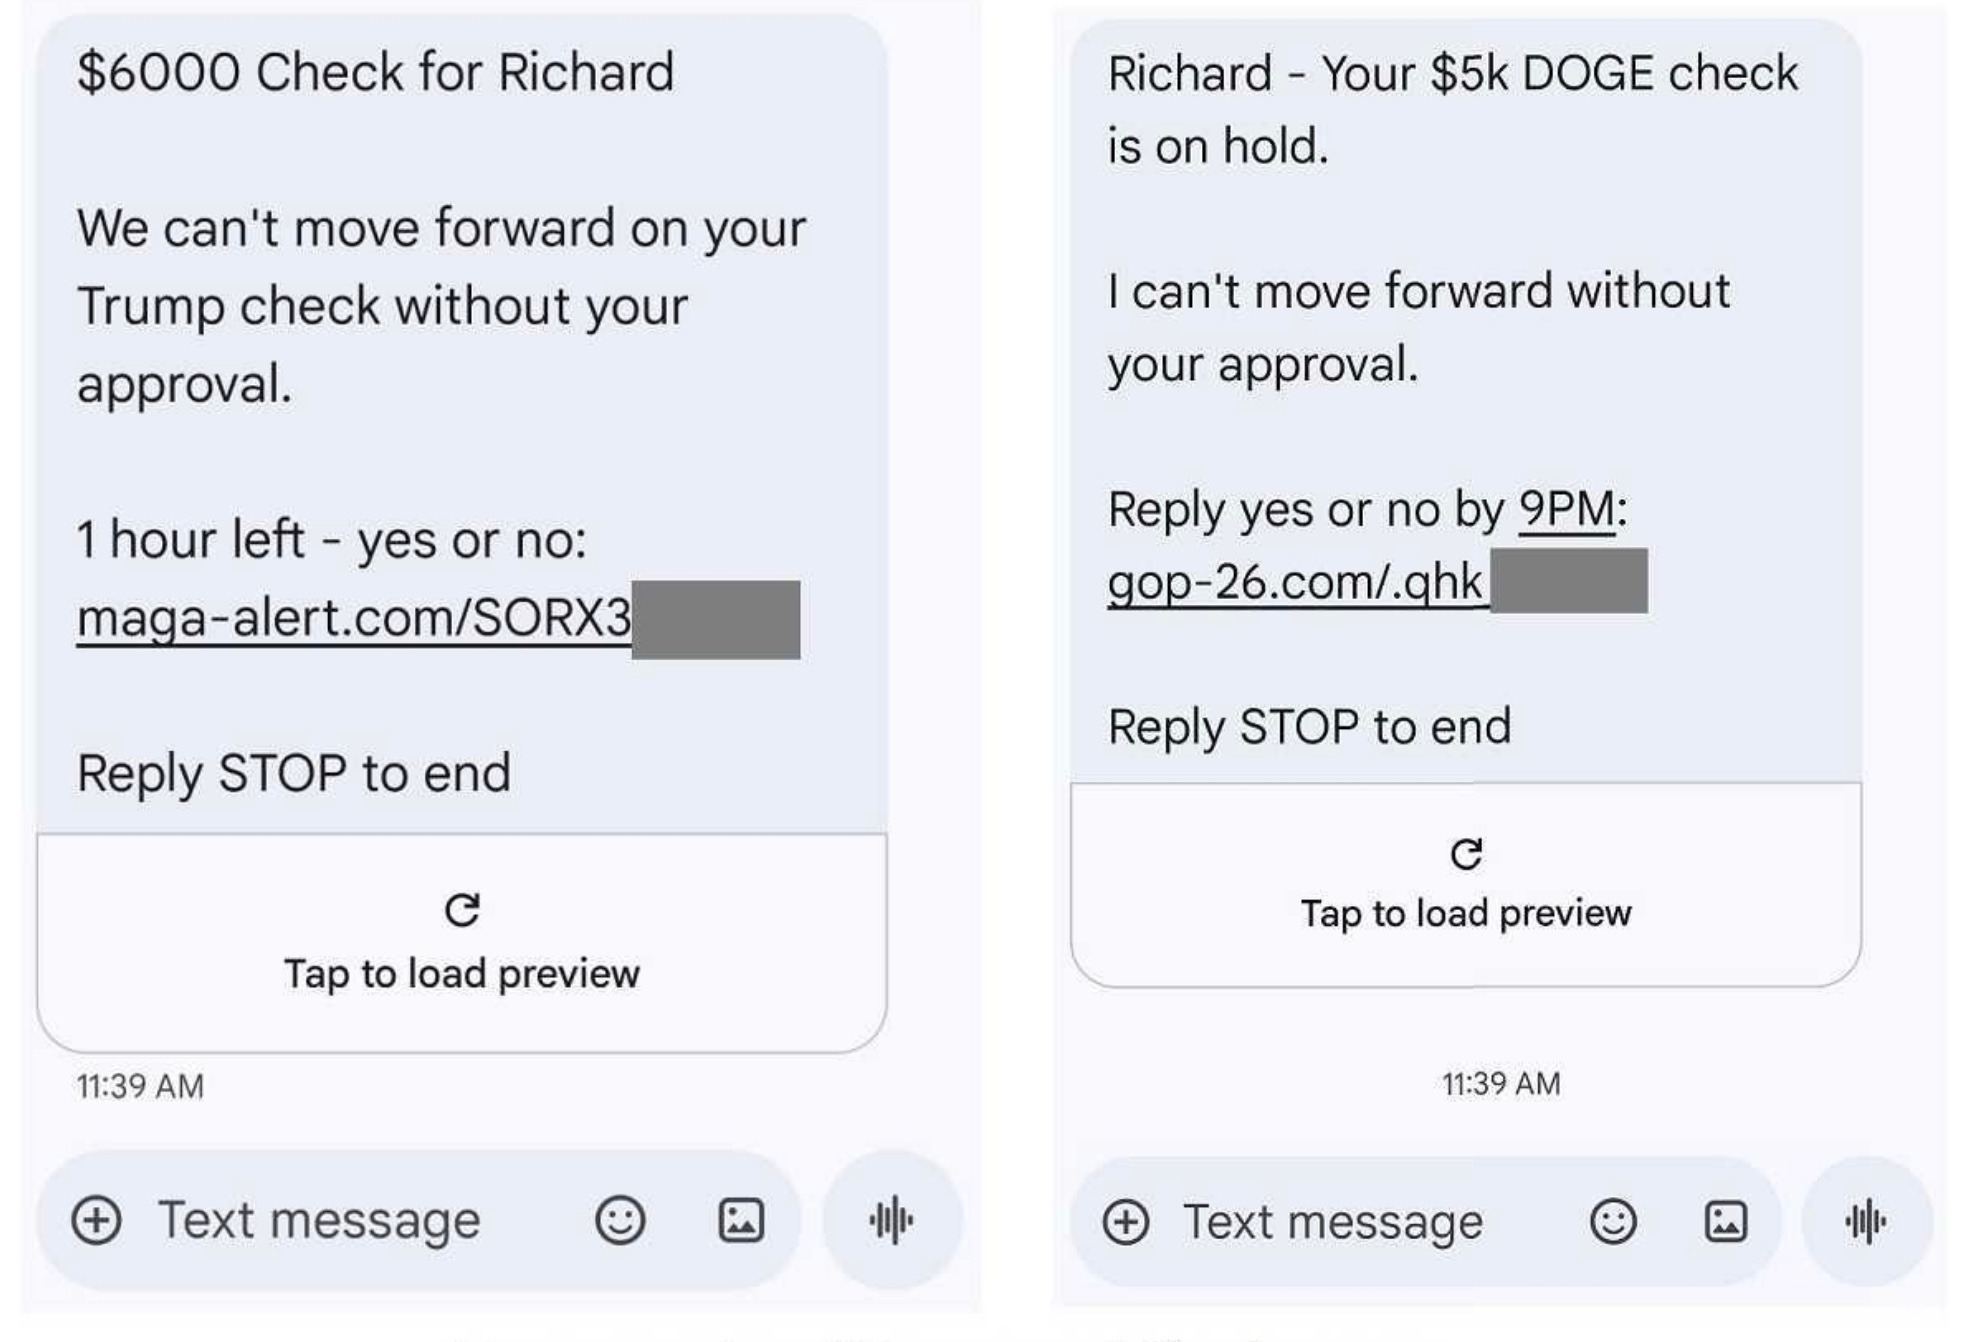
Protect Yourself From Scams
Joe Zarzycki, CIMA®, Managing Director of Institutional Wealth at BNA, encourages families to use only official government channels when opening or activating accounts. Avoid unsolicited calls, emails, or text messages requesting your child's Social Security number or other personal information.
Understand Withdrawal Restrictions
Joe also emphasizes that Trump Account funds generally cannot be withdrawn before the calendar year a child turns 18, with limited exceptions. Unlike a 529 education savings plan, which allows earlier withdrawals, Trump Account funds are generally inaccessible during childhood.
Once the child reaches the calendar year they turn 18, traditional IRA rules generally apply. Early withdrawals may be subject to income taxes and penalties, although certain exceptions may apply.
Whether you're considering a Trump Account, comparing it with a 529 plan, or reviewing your family's savings strategy, BNA's tax and wealth advisory teams can help you understand your options.
Connect with BNA Wealth to learn more.
For official information, visit IRS.gov/TrumpAccounts.
This article is for general informational purposes only and does not constitute individualized tax, legal, or investment advice. Eligibility, contribution limits, tax treatment, and withdrawal rules are subject to change. Investments involve risk, including potential loss of principal.
Discover how our team can support your financial goals with clarity and precision.